Cleobetra KYC Verification: Documents, Checks and Timing
 Available in US
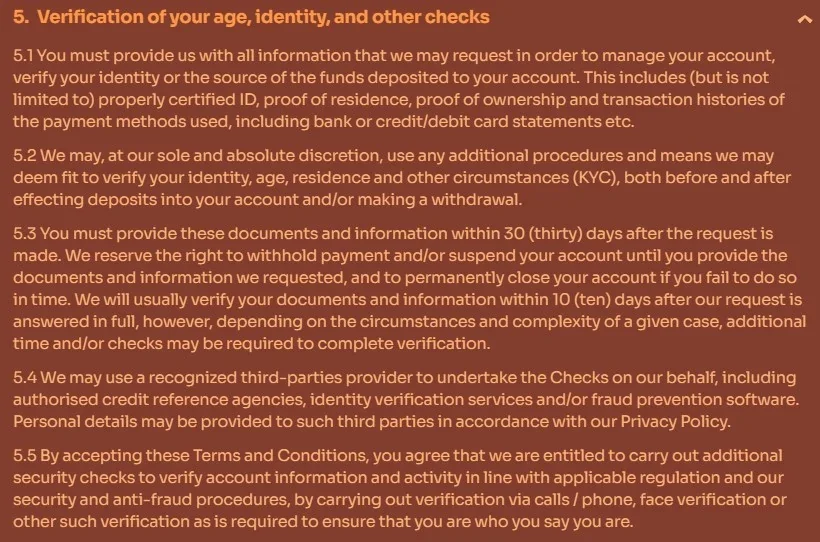
Cleobetra’s current terms say identity and source-of-funds checks can happen before or after deposits and withdrawals. The official examples of information that may be requested include properly certified identification, proof of residence, proof that a payment method belongs to the account holder, and transaction histories such as bank or card statements. These are examples from the policy, not a guaranteed checklist for every account.
The timing has two separate stages. Requested documents and information must be supplied within 30 days. After Cleobetra receives a complete response, the terms say documents and information are usually verified within 10 days, although additional time or checks can be required. The word “usually” matters: 10 days is not a guaranteed completion deadline.
Table of Contents
- What Cleobetra can ask for during KYC
- When KYC can happen
- The 30-day response period and usual 10-day verification period
- How KYC interacts with withdrawals
- Payment-method ownership checks
- What the official terms do not justify claiming
- A practical KYC preparation checklist
- KYC and regulatory status are separate
- Mobile verification and account access
- Bottom line on Cleobetra KYC
What Cleobetra can ask for during KYC
The current General Terms and Conditions place KYC under “Verification of your age, identity, and other checks”. The wording is broad because Cleobetra can request information needed to manage an account, verify identity or check the source of deposited funds. Within that broad power, the terms give specific examples that are useful for preparation.
| Official example | What it is intended to establish | Important limitation |
|---|---|---|
| Properly certified ID | Identity and age | The terms do not say every user receives the same document request. |
| Proof of residence | Current residential details | The general KYC clause does not provide one universal list of acceptable proof-of-address documents. |
| Proof of payment-method ownership | That the funding or withdrawal method belongs to the account holder | The exact proof required can depend on the method used. |
| Payment transaction histories, bank or card statements | Payment activity and source-of-funds review | The requested period or exact statement format is not fixed in the general KYC clause. |
This distinction prevents a common KYC mistake. A list of examples in the terms should not be rewritten as a mandatory four-document bundle. Cleobetra can ask for these items, but the account-specific request is the operative checklist. If support asks for a different or additional security check that is permitted by the terms, the examples above do not override that request.
The terms also allow checks of identity, age, residence and other circumstances through additional procedures. They mention third-party identity or fraud-prevention services and state that further security checks can include phone calls or face verification. Those provisions show why a static document list cannot predict every verification path.
When KYC can happen
Cleobetra does not confine verification to account opening. Its current terms expressly allow KYC both before and after deposits and withdrawals. For an Australian reader, the practical consequence is that a successful registration or deposit should not be interpreted as proof that all checks are finished.
Verification can become relevant when money is moved because the terms connect payment activity to identity, payment-method ownership and source-of-funds checks. A user who has already deposited may still receive a document request before a withdrawal is completed. Equally, the operator can conduct checks earlier if it considers them necessary.
That is why the separate Cleobetra account guide treats signup and KYC as two related but distinct workflows. Registration establishes the account and the account holder’s obligations. KYC is an ongoing verification power that can be used later, especially around financial activity.
The 30-day response period and usual 10-day verification period
The most important timing point is that Cleobetra publishes two clocks, not one. First, the user must provide requested documents and information within 30 days after the request. The terms allow the operator to withhold payment or suspend the account while requested information is outstanding, and they reserve the right to close the account if the information is not supplied in time.
Second, after the request has been answered in full, the terms say Cleobetra will usually verify the documents and information within 10 days. The same clause immediately qualifies that statement by saying additional time and checks can be required depending on the circumstances and complexity of the case.
How to read the timing correctly
Timing: 30 days is the stated period for the customer to provide requested material. Usually within 10 days describes the operator’s verification after a full response. Neither figure means that every KYC case will finish 10 days after the first email, and neither is a guaranteed withdrawal-arrival date.
A useful preparation step is therefore to answer a request as a complete package rather than sending one item at a time when several items were requested. The terms tie the usual 10-day wording to the point at which the request has been answered in full. That makes completeness materially different from simply opening or acknowledging a KYC request.
How KYC interacts with withdrawals
Cleobetra’s withdrawal terms say requests are worked through by the financial department within three business days after the request is made, or after the previous withdrawal is paid, provided the other conditions are met and checks are complete. The terms separately allow withdrawal processing to be delayed while identity, account balance, source-of-funds and Terms compliance checks are performed.
This means the three-business-day wording should not be added mechanically to the KYC timing and treated as a guaranteed payout formula. If verification is incomplete, the withdrawal review can wait for those checks. After Cleobetra works through a transfer, the receiving payment provider can also add settlement time.
The detailed AUD VIP ceilings, pending-request cap and rollover rules are covered in the withdrawal limits guide. The key point here is narrower: KYC is one of the conditions that can determine when a withdrawal becomes ready for normal financial processing.
Payment-method ownership checks
One unusually useful detail in the current KYC wording is the direct reference to proof of ownership and transaction histories of payment methods used. That makes payment consistency important. The terms also state elsewhere that the credit card or other payment method used to fund the account must belong to the account holder.
For practical preparation, keep records that identify the account holder and the relevant payment relationship without exposing unnecessary data. What Cleobetra actually asks for should control what is submitted. Cleobetra’s general KYC clause does not set one universal specification for card photos, bank-statement date ranges, file formats or redaction rules, so follow the live request for those details.
For the broader deposit-method context, use the Cleobetra payments guide rather than assuming that every payment option triggers identical ownership checks.
What the official terms do not justify claiming
- Cleobetra is not a “no KYC” casino under the current terms.
- The listed document examples are not an exhaustive checklist for every user.
- The 10-day wording is not a guaranteed maximum verification time.
- A completed deposit does not prove that future verification will not be requested.
- A KYC request does not by itself prove that a withdrawal has been rejected.
Keeping those boundaries clear matters because KYC pages often become misleading by turning examples into promises. The practical approach is to use Cleobetra’s published examples and timing, understand where the process can affect withdrawals, and follow account-specific requests in the live verification workflow.
A practical KYC preparation checklist
- Make sure the personal details in the account remain accurate and current.
- Use payment methods that belong to the account holder.
- If a KYC request arrives, identify every item requested before replying.
- Provide the requested information within the stated 30-day period.
- Do not assume the 10-day usual verification period starts before the response is complete.
- Keep copies of the material submitted and the request that prompted it.
- If a withdrawal is pending, treat verification and payment processing as separate stages.
This checklist is based on the current terms rather than on a guessed universal document workflow. It is designed to reduce avoidable back-and-forth while staying within what the source actually says.
Before submission, compare the request with the files prepared and confirm that each requested item has been addressed clearly.
KYC and regulatory status are separate
KYC is an account-verification process and does not determine the regulatory status of the service. It should therefore be assessed separately from the product’s regulatory position in Australia. For the separate Australian regulatory assessment, see the dedicated Australian licence status guide.
Mobile verification and account access
KYC requests may be encountered on mobile as well as desktop. Cleobetra’s current public site supports browser use and home-screen shortcut access; the separate Cleobetra mobile guide explains that access model.
Any published verification image should omit personal details, balances, document numbers and account-specific identifiers. The image should illustrate the policy or interface without exposing a user’s identity.
Bottom line on Cleobetra KYC
Cleobetra’s current terms give unusually concrete KYC information. Checks can occur before or after deposits and withdrawals. Official examples include certified ID, proof of residence, proof of payment-method ownership and transaction histories or statements. Requested information must be supplied within 30 days, and verification is usually completed within 10 days after a full response, with extra time possible where more checks are required.
Those points are enough to prepare without inventing a universal checklist or guaranteed processing time. For the full site-level assessment, return to the Cleobetra review Australia.
These document examples, trigger points and timing are based on Cleobetra’s current General Terms and Conditions. The short Australian regulatory note is based on ACMA’s April 2026 blocking notice.
Written by the editors at Cleobetra Casino.